
ConnectEBT
- Rating
- 4.6
- Downloads
- 1.00M
- Content Rating
- Everyone
ConnectEBT - Screenshots
Pros
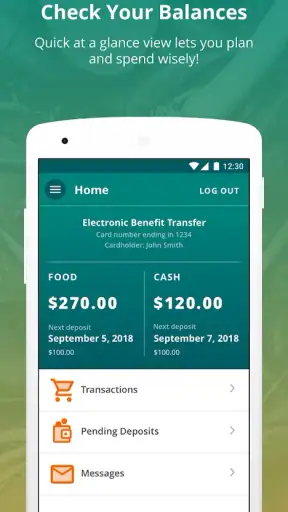
- Quickly check SNAP and cash benefit balances on your phone.
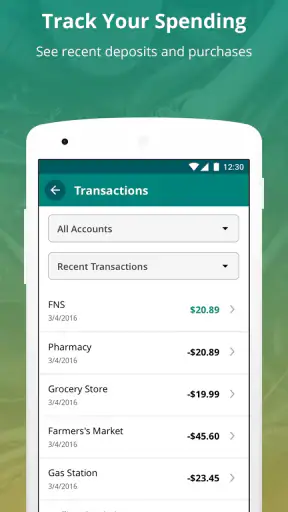
- Shows recent transactions to help track household spending.
- Provides access to benefit details without visiting an office.
- Can help identify unfamiliar purchases or possible card misuse.
- Useful for managing benefits while shopping or away from home.
Cons
- Availability and features may vary by state or participating program.
- Requires an internet connection for current balance information.
- Login or verification issues can delay access to account details.
- Transaction updates may not appear immediately after a purchase.
- Some users may find the interface less intuitive on smaller screens.
ConnectEBT - Description
- App Name
- ConnectEBT
- Package Name
- com.conduent.ebt
- Developer
- Conduent Incorporated
- Category
- Finance
- Last Updated
- Apr 19, 2017
- Version
- 2.4.0(20260612)
Managing SNAP and Cash benefits is one of those tasks that should take a few moments, not a trip through several confusing screens. ConnectEBT is built for that narrow, practical job: it lets me access my EBT account information from a mobile device. After using it as a finance app, I see its main value in reducing the need to rely on memory when I am shopping, checking whether funds are available, or trying to understand what happened after a recent purchase.
The app comes from Conduent Incorporated and is free to use. Its audience is broad because it carries an Everyone age rating, but the real audience is much more specific: people who receive SNAP or Cash benefits through an EBT account and want a simpler way to check account information. It is not a general banking replacement, a budgeting suite, or a grocery-planning tool. That focused purpose is both its strongest quality and the reason some readers may find it too limited.
What ConnectEBT feels like in everyday use
A focused way to check benefits without guesswork
My first impression is that ConnectEBT makes the most sense when I treat it as an account-checking companion rather than an all-purpose financial app. The useful question is usually immediate: how much is available, and what does the recent account activity show? Having that information on a phone is more convenient than depending on a paper receipt, remembering a previous balance, or waiting until the next shopping trip to discover a problem.
A realistic example is a grocery run after several smaller purchases during the week. Instead of estimating the remaining SNAP balance, I can open the app before reaching the checkout and make a more informed decision about what to put in the cart. The same habit can help when managing Cash benefits, especially if several expenses have made the available amount harder to track. The app does not replace careful budgeting, but it can make the starting information easier to access.
The most useful habit is checking before a decision, not after a declined transaction. I would open ConnectEBT before shopping, after a purchase that looks unusual, and whenever a receipt does not match what I expected. That turns the app into a small verification step in my routine instead of something I only remember when there is already a problem.
Speed expectations: quick for a narrow task, dependent on the moment
ConnectEBT is the kind of app where perceived speed matters because users often open it in a hurry. At a store, I do not want to spend several minutes navigating through unrelated financial tools. Its focused role gives it a reasonable advantage over a conventional banking app, which may present checking accounts, cards, transfers, alerts, and other material before I reach the information I actually need.
Still, I would not judge its speed only by how quickly the app opens. Account information has to load, and that experience can depend on the phone, the connection, and the service handling the account request. A screen appearing instantly is not the same as current balance information being ready. For that reason, I recommend opening it while still in the parking lot or at home rather than waiting until the payment terminal is already waiting.
One practical tip is to avoid treating a slow response as proof that the balance is unavailable or unchanged. If the information takes longer than expected, I would give the request time to complete and compare it with the most recent receipt before making a second attempt. Repeatedly tapping buttons can make a stressful moment harder to interpret, particularly when the user is standing in a busy checkout line.
Heavy-use moments expose the real trade-offs
The busiest moments for an app like this are not necessarily long sessions. They are short bursts when many people need account information at once, or when a user is checking repeatedly after several transactions. ConnectEBT is designed around access to EBT SNAP and Cash account information, so its usefulness depends on that information being available when the user needs it most.
I would be especially deliberate around benefit-related shopping days, travel between stores, or a period when several household members are using the same account. A single balance check may be enough for one person, but a household that makes multiple purchases can benefit from recording the balance after each important transaction. That simple workflow reduces the temptation to rely on a possibly outdated mental estimate.
There is also a trade-off between convenience and overchecking. Opening the app after every minor purchase may create more anxiety than clarity. I find it more sensible to use it at meaningful points: before a larger grocery trip, after a transaction that seems incorrect, and when planning how much of the remaining benefit to allocate. The app is most helpful when it supports a routine rather than becoming the routine itself.
Reliability means knowing what to verify
For a finance app, reliability is not just whether the interface stays open. It is whether I can trust the displayed account information enough to act responsibly. ConnectEBT gives me a convenient place to review SNAP and Cash account details, but I would still keep receipts for purchases that matter. A receipt provides a useful reference if the balance looks unexpected or if I need to compare the timing of a transaction.
This is one of the app’s less obvious strengths: it can help me notice discrepancies earlier. If I normally check only at the checkout, I may not recognize a problem until I am trying to pay. Checking before shopping and retaining the receipt gives me two points of comparison. That does not solve every account issue, but it creates a clearer record of what I expected and what appeared afterward.
I also would not use a single delayed screen as the only basis for a serious financial decision. If the displayed information conflicts with a recent receipt, I would pause, check again later, and use the appropriate official support route for the account if the mismatch remains. In my view, that is not a criticism unique to this app; it is a sensible rule whenever a mobile screen is being used to guide a real transaction.
Device constraints and the minimum practical setup
The current version is 2.4.0(20260612), and the app requires at least iOS 10. That makes the device requirement relatively approachable for people using an older compatible Apple device, although the age of a phone can still affect the overall experience. A device with limited storage, an aging battery, or an unreliable connection may make any account-checking task feel more frustrating, even when the app itself is straightforward.
I would keep the operating system supported, leave enough free space for normal app updates, and avoid relying on the app for the first time during an urgent purchase. Installing it and signing in before a busy shopping trip gives me a chance to learn the layout and confirm that the account information is accessible. This is particularly important for someone who is less comfortable with mobile finance tools.
Resource demands are best understood through the app’s narrow purpose. ConnectEBT does not need to be open for long periods, and I would not expect a benefit-account checker to be used like a streaming or navigation app. The sensible approach is to open it when needed, review the information, and close it. That keeps the app’s role clear and avoids mistaking a short account check for a full financial-management session.
Where it compares well with usual alternatives
The usual alternatives are calling an account information line, checking a receipt, asking at a service point, or using a broader banking application when one is available. ConnectEBT is more convenient than a phone call for a quick balance review because I can check it privately and without waiting through a conversation. Compared with a receipt, it is better for checking before a purchase rather than only seeing information after the transaction.
A general banking app may be better for someone who wants one place for budgeting, bill payments, bank accounts, and spending analysis. ConnectEBT is not trying to compete on that ground. Its advantage is concentration: it is aimed at SNAP and Cash account information, so users do not have to search through unrelated banking features. The downside is that I still need another tool for broader household budgeting.
Paper records remain useful as a backup. A receipt can show what happened at a particular purchase, while the app is more convenient for checking the account from a phone. I would use both rather than choosing one exclusively. That combination is especially valuable when a transaction needs to be questioned later, because the app gives me current account context and the receipt gives me a concrete purchase reference.
Who will benefit most from it
ConnectEBT is a good fit for someone who regularly checks SNAP or Cash account information and wants a mobile option that stays focused on that task. It is also useful for people who shop at different times or locations and do not want to carry an older receipt just to remember an approximate balance. A caregiver or household organizer may appreciate having a quick way to check information before planning a larger purchase.
It can also help users who are trying to build a more reliable shopping routine. For example, I would check the account before making a weekly list, confirm the balance after the main trip, and keep the receipt if the amount seems unexpected. That workflow does not require a separate spreadsheet, and it gives me enough checkpoints to catch mistakes without turning every purchase into an accounting project.
The app is less suitable for someone looking for detailed spending categories, long-term financial goals, bill management, or a complete view of several accounts. A budgeting app or full banking service would be better for those needs. I would also hesitate to recommend relying on it alone to someone who has an old or unstable device and no practical backup method for checking account information.
Privacy, access, and recovery habits
Because ConnectEBT deals with benefit-account information, I would use it thoughtfully on shared phones. I would avoid leaving the device unlocked in public, review what appears on the screen before showing it to someone else, and sign out or secure the phone according to my normal habits when other people can access it. These are simple precautions, but they matter more for an account app than for a casual shopping app.
A useful recovery plan is to keep recent receipts and know where to seek help if access fails. If the app does not load during a checkout, I would not keep retrying blindly while holding up the line. I would use the information already available to me, complete the purchase only if I am confident it is appropriate, and investigate the account afterward. Having that plan reduces pressure and prevents a temporary technical problem from becoming a rushed financial decision.
For a new user, I would install the app at a calm time, complete the account setup, and perform a normal balance check before depending on it. That first session is also the right time to learn how account information is presented and where recent activity appears. The benefit of this preparation is not a hidden feature; it is the confidence that comes from knowing what a normal screen looks like before something unexpected happens.
Adoption, cost, and the maturity of the app
ConnectEBT has been available since Apr 19, 2017, and its current listing shows over one million installs. It carries a 4.6 average from around nineteen thousand ratings, with roughly seven and a half thousand written reviews. Those figures suggest that it has reached a substantial audience and that many users find its focused purpose worthwhile, while the written feedback also reflects the kind of real-world expectations people bring to a benefits app.
The price is free, which is important for an app serving people who are already managing limited household resources. There is no purchase decision to make before trying it, so I can evaluate whether it fits my account and routine without adding another expense. I would still judge it by usefulness rather than cost alone: a free app is valuable only when it gives me dependable access at the moments I need it.
The Everyone rating is appropriate for a tool that provides account information rather than entertainment aimed at a particular age group. Even so, younger users or anyone helping a family member may need guidance during setup and when interpreting account activity. The app can make information easier to reach, but it does not remove the need to understand what a balance means or how a particular transaction affects available benefits.
My performance verdict
After weighing speed, heavy-use situations, reliability, and device constraints, I see ConnectEBT as a practical specialist rather than a complete finance platform. Its performance value comes from getting me to SNAP and Cash account information without the clutter of a general banking app. That focus makes short checks easier to fit into real life, especially before shopping or when a receipt raises a question.
I would recommend it to eligible EBT users who want a free mobile way to review account information and are willing to keep receipts as a sensible backup. I would not recommend treating it as a budgeting system, assuming every delayed display should be trusted without verification, or depending on it without first testing access on the device. Those limits are important, but they do not erase the app’s central usefulness.
My final view is that ConnectEBT earns its place when the goal is quick, focused EBT account awareness. It is not flashy, and it does not need to be. If I use it as one part of a careful routine—check before shopping, compare after important purchases, and keep a recovery plan—it can remove a lot of uncertainty from everyday benefit management. For broader financial planning, I would pair it with a separate budgeting tool; for the specific job it is built to handle, I find it a sensible choice.
FAQ
What is ConnectEBT and what can I use it for?
ConnectEBT is a mobile app designed to help eligible benefit recipients manage an Electronic Benefit Transfer (EBT) account from a smartphone. Depending on the participating state or program, you can generally check your available balance, review recent transactions, view deposits, and locate useful account information. Available features may vary by location, so the app’s options should be checked after selecting the correct state or program.
Is ConnectEBT available in every state and for all EBT programs?
ConnectEBT availability depends on the state and the specific EBT program being used. Some states support the app for programs such as SNAP or cash assistance, while others may use a different official application or web portal. Before downloading, confirm that your state appears in the supported list and that your benefit card is compatible. Regional availability and supported services can change over time.
Can I check my EBT balance and transaction history with ConnectEBT?
In supported regions, ConnectEBT allows users to view their current benefit balance and review recent account activity directly from the app. This can make it easier to confirm deposits and identify purchases without calling customer service. Keep in mind that balances and transactions may not update instantly, and the information shown can depend on the state system, card type, and network connection.
How do I protect my personal information when using ConnectEBT?
Because ConnectEBT may involve benefit account details and personal information, use it only on a trusted device and download it from an official app store. Create a strong, unique login password, enable device security such as a PIN or biometric lock, and avoid sharing verification codes. Never provide your card number or account credentials through suspicious messages, links, or unofficial support channels.
What should I do if ConnectEBT does not work or my card is lost?
If the app fails to load, shows outdated information, or will not accept your login, first check your internet connection, update the app, and try again later. For account access, card replacement, suspicious transactions, or a lost or stolen EBT card, use the official customer-service number or website associated with your state. The correct support process can vary, so avoid relying on unofficial contact details.


